Puff Back Damage Insurance Claims on Long Island — What You Need to Know
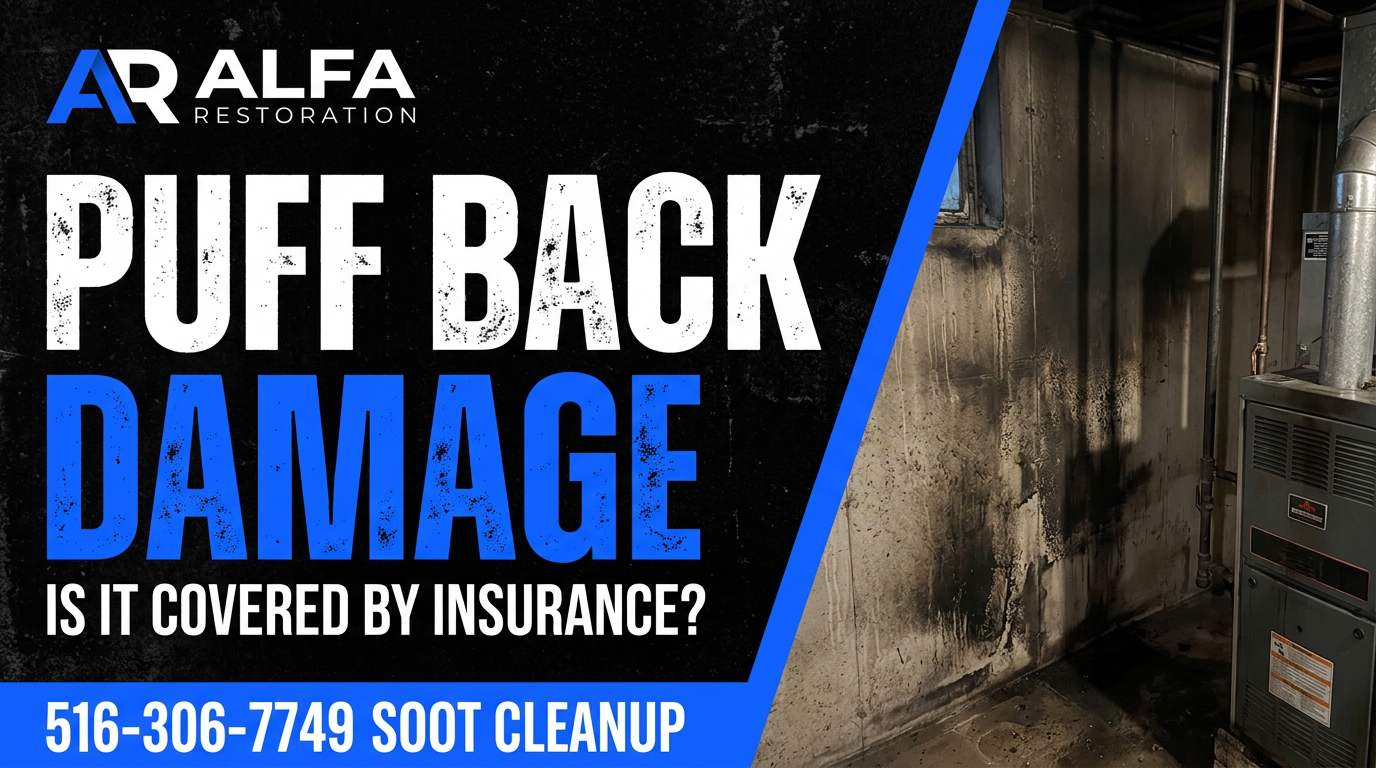
If your oil burner just blew soot through your entire Long Island home, you're probably staring at a sea of greasy black residue covering every wall, ceiling, fabric, and piece of furniture you own — and wondering: does insurance cover this?
The good news: yes, almost always. Standard NY homeowners insurance treats puff backs as sudden, accidental mechanical events — and most policies pay out fully, often $10,000–$30,000+, for a covered puff back claim.
The bad news: insurance carriers know puff back claims are complex, and they often try to underpay them. This guide walks you through exactly how to file, what to document, and how to make sure your full damage gets covered.
What Is a Puff Back? (Insurance Definition)
For insurance purposes, a puff back is a sudden, accidental discharge from an oil burner caused by a misfire, ignition failure, or combustion chamber malfunction. The result is soot, oil residue, and combustion byproducts blown through your HVAC system and out every register, vent, and seam in your home. Insurance companies recognize three key elements: sudden (happens in seconds, not over time), accidental (not caused by negligence or maintenance failure), and mechanical (originated from your heating system). If all three apply, you have a covered claim under standard HO-3 and HO-5 policies.
What's Covered in a Puff Back Insurance Claim
Most Long Island puff back claims include soot cleanup (surface cleaning of every wall, ceiling, floor, fixture in affected areas), content cleaning and pack-out (off-site or on-site cleaning of clothing, furniture, electronics, books, art — often the largest line item), HVAC and duct cleaning, drywall sealing and repainting with stain-blocking primer, carpet/upholstery/fabric cleaning or replacement, odor elimination via thermal fogging, ozone treatment, and hydroxyl generators, temporary living expenses (Loss of Use coverage typically provides 20% of dwelling coverage — often $50,000–$120,000), and reconstruction if needed for severe puff backs.
What's NOT Covered
Negligence and lack of maintenance. If your insurance carrier can prove your oil burner was unmaintained — no annual tune-up, ignored warning signs, deferred repairs — they can deny the claim. Annual oil burner service is essential. The oil burner itself isn't replaced by your homeowners policy; that's covered (if at all) by your equipment warranty or service contract. Pre-existing soot damage from previous, smaller puff backs that weren't reported may be excluded.
How Much Do Puff Back Claims Pay on Long Island?
Typical Long Island puff back insurance settlements: light puff back (single floor, contained) $3,000–$8,000; moderate puff back (whole home, HVAC contamination) $8,000–$20,000; severe puff back (extensive content cleaning, full repaint, reconstruction) $20,000–$50,000+. These numbers assume a properly documented claim. Underdocumented claims often settle for 40–60% of the actual cleanup cost.
How to File a Puff Back Insurance Claim — Step by Step
Step 1: Don't turn the heat back on. Until your oil burner is inspected and serviced, another puff back can happen. Stay warm with space heaters or relocate temporarily. Step 2: Document everything before cleaning. Photo and video every room, every surface, every affected item. Time-stamp everything. The soot pattern itself is evidence. Step 3: Call your insurance carrier. Report the loss. Get the claim number. Note the date, time, and adjuster's name. Step 4: Call a puff back restoration specialist — not a general cleaning company, but a restoration company that handles puff backs specifically and bills insurance directly. Step 5: Get the oil burner serviced by a licensed technician and keep the receipt. Step 6: Meet the insurance adjuster with your restoration contractor present. Adjusters often underestimate puff back damage by 30–50%. Step 7: Approve the scope and start the work.
Common Puff Back Claim Mistakes Long Island Homeowners Make
Trying to clean it themselves. Wet cleaning sets oil-based soot permanently into surfaces. DIY almost always increases the final restoration cost. Not documenting before cleanup. No photos, no proof. Hiring a general cleaning company. Standard cleaners don't have IICRC fire and smoke certification or the equipment for HVAC cleaning — their work fails and the smoke smell returns in 30 days. Accepting the first settlement offer when adjusters often offer 50–70% of true cleanup cost. Skipping content cleaning and leaving thousands of dollars in salvageable belongings unrestored.
Frequently Asked Questions
Does homeowners insurance always cover puff back damage? Almost always, yes — under standard NY HO-3 and HO-5 policies. The exception is documented negligence or lack of maintenance.
How long does a puff back insurance claim take to settle? Initial settlement: 2–4 weeks. Full claim closeout (after work completes): 6–12 weeks.
Can I stay in my home during puff back cleanup? Often no — soot contamination and odor make most homes temporarily uninhabitable. Loss of Use coverage pays for hotel and ALE.
What if my insurance company denies my puff back claim? Document everything, get a written denial reason, and consider hiring a public adjuster or contacting a NY insurance attorney. Most denials are reversible with proper documentation.
How do I prevent another puff back? Annual oil burner service, prompt response to any unusual sounds or smells, and replacing aging burners (15+ years old) with newer high-efficiency models.
Puff back on Long Island? Alfa Restorations handles cleanup AND your insurance claim. Call (516) 306-7749.