Water Damage vs. Flood Damage: Why the Difference Could Cost You Thousands
When a homeowner calls us soaking wet and panicked, one of the first questions we ask isn't about the damage — it's about the source. Because in the eyes of your insurance company, "water damage" and "flood damage" are two completely different things, covered by two completely different policies, and confusing them can cost you tens of thousands of dollars.
Here's what every homeowner needs to understand before disaster strikes.
The Definition That Decides Your Claim
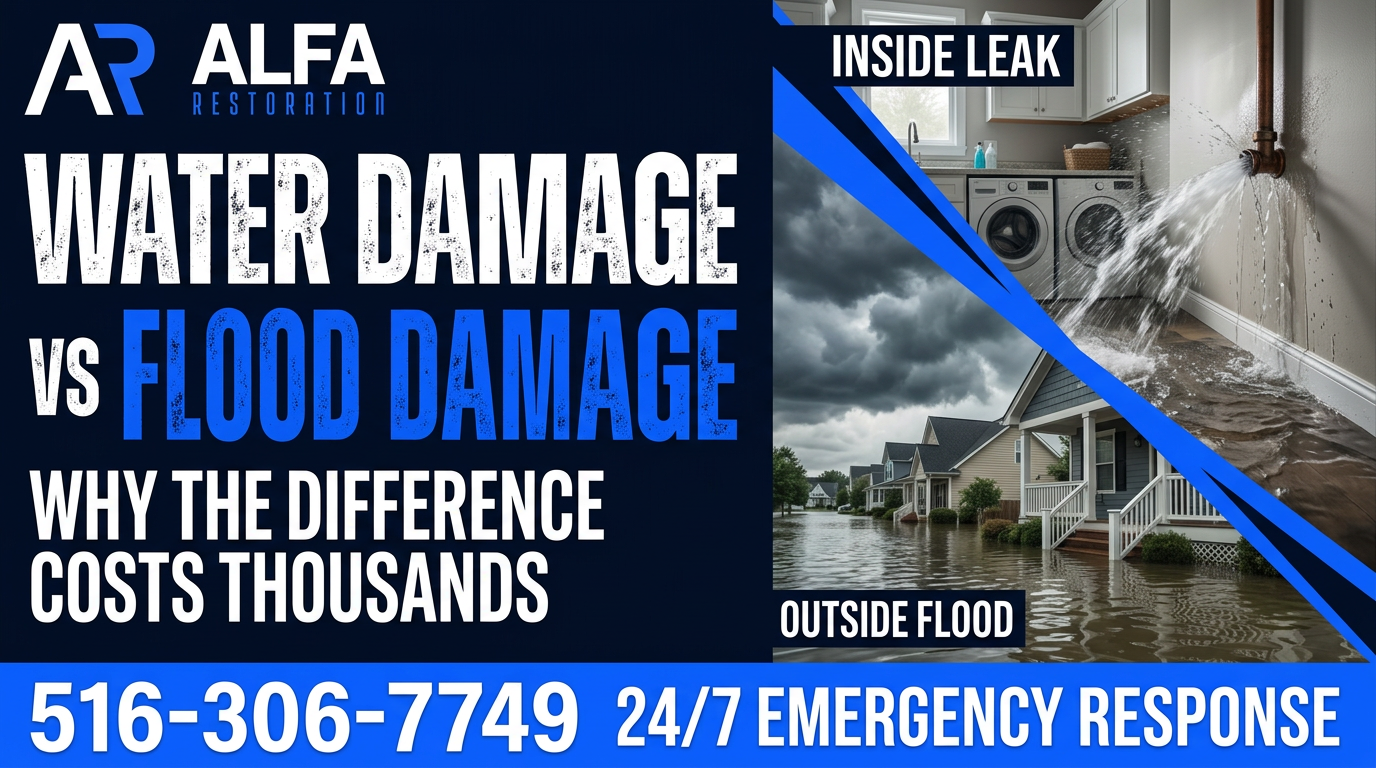
In insurance language, flood damage has a very specific meaning: water that comes from outside your home and rises from the ground up. A storm surge, an overflowing river, a hurricane-driven flood, heavy rainfall that pools in your yard and seeps in through the foundation — all flood damage. The defining feature is that the water originates outside your property and reaches your home naturally.
Water damage is everything else. A burst pipe, a leaking water heater, an overflowing washing machine, a roof leak from a windstorm, a backed-up dishwasher — all water damage. The defining feature is that the water originates inside your home or comes from a sudden, accidental event involving your property.
Why does this matter? Because a standard homeowners insurance policy almost always covers water damage. It almost never covers flood damage.
The Coverage Gap That Surprises Most Homeowners
Roughly 85% of American homeowners have homeowners insurance. Fewer than 15% have flood insurance. Yet flooding is the most common natural disaster in the United States, and even one inch of floodwater can cause $25,000 or more in damage.
Flood insurance is a separate policy, sold primarily through the National Flood Insurance Program (NFIP) and a handful of private insurers. If you live in a designated high-risk flood zone and have a federally-backed mortgage, you're required to carry it. If you don't, you probably don't have it — and most homeowners only find out after a flood happens.
There's also a 30-day waiting period on most new flood policies. You cannot buy flood insurance the day before a hurricane and expect coverage. Planning ahead is the only option.
The Gray Areas Where Claims Get Denied
The line between water and flood damage gets blurry fast, and insurance companies are very good at finding the blurry parts.
If a hurricane blows shingles off your roof and rain pours into your attic, that's typically water damage, covered by homeowners insurance. But if the same hurricane causes a storm surge that floods your first floor, that's flood damage, covered only by flood insurance. The same storm can produce two claims under two different policies — or one claim that gets denied entirely.
If a sewer backs up into your basement after a heavy rainstorm, you might think it's flood damage, but it's typically considered water damage from sewer backup — and most standard policies exclude it unless you've added a specific sewer backup endorsement.
If groundwater seeps through your foundation after weeks of rain, it's almost always classified as flood damage, even though no visible flood ever occurred outside.
This is where having a restoration company that understands insurance becomes critical.
How Alfa Restorations Helps You Win Your Claim
We don't just dry out your home. We document the source, the spread, and the extent of damage in a format insurance adjusters trust. We use moisture mapping, thermal imaging, and detailed photo logs that make it harder for an adjuster to underpay your claim. We work directly with your insurance company so you don't have to translate technical language while you're already overwhelmed. And when claims are denied or underpaid, we provide the documentation that supports an appeal.
In our experience, the difference between a fully paid claim and a denied one often comes down to how the initial loss was documented in the first 24 hours.
What to Do Right Now
Pull out your homeowners policy and look for the words "flood exclusion" — they're in there. If you don't have separate flood insurance and you live anywhere that experiences hurricanes, heavy rain, or rising rivers, get a quote today. The 30-day waiting period means tomorrow is too late.
If you're already dealing with damage and you're not sure how it will be classified, call us before you call your insurance company. We'll inspect the source, give you a clear picture of what you're dealing with, and help you frame the claim correctly from the start. Call Alfa Restorations at (516) 306-7749 for a free inspection.